
Quick & simple note today:
Recently, I’ve been enjoying conversations about “The Path.”
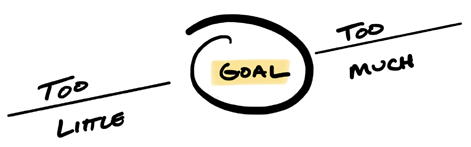
We believe that goals should be date-specific and dollar-specific.
For example, I want to have $140,000 in May 2032 to pay for my current 12-year-olds future education.
A quick time value of money calculation will tell me that if I have $60,000 saved today, I will need to invest approximately $485/month assuming a 7.8% rate of return over the next 6 years.
If I can only save $350/mo, that’s still great, but then I’m pushing the risk I don’t have enough money saved for his education expenses and either I must find an alternative option in the future or he might have to pay for the cost of education himself via student loans.
Going the other direction, the hidden risk that few people think about is over funding the plan.
I know that might sound odd coming from a financial planner, but there’s a cost of saving too much.
The cost would be missing on opportunities today, because you’re setting too much aside for a future goal that you’re already likely to hit
One of the core strengths of Know My Plan is helping people find an adequate savings rate that historically gives us a high probability of funding the underlying goals within the plan.
Never perfect, but directionally correct.
Do we help people save? Of course!
But we also help people spend (hopefully guilt free).
It all starts with a plan. Stay disciplined. Work the plan.
–Nic
Investing involves risk and you may incur a profit or loss regardless of strategy selected. Prior to making an investment decision, please consult with your financial advisor about your individual situation. Every investor’s situation is unique and you should consider your investment goals, risk tolerance and time horizon before making any investment. The forgoing is not a recommendation.